Last Updated: November 19, 2026
Quick Summary
Moving insurance coverage ranges from basic liability, which pays by weight, to full value protection, which covers repair or replacement cost. Third-party moving insurance can fill gaps beyond the mover’s liability. The right choice depends on what you own and its replacement value.
- Basic liability coverage pays based on weight rather than the actual value of damaged items.
- Full value protection covers the repair, replacement, or market value of damaged or lost items.
- Call your homeowner or renter’s insurer to check whether belongings in transit are covered.
- Read the declared value section of your bill of lading, since it controls any claim.
- Report damage at delivery, photograph it, and file a written claim before the deadline.
Table of Contents
- Why Moving Insurance Coverage Matters Before Moving Day
- Basic Liability Coverage: What Movers Owe You by Default
- Moving Insurance vs. Valuation Coverage: Know the Difference
- Full Value Protection Moving: How It Works and Who Needs It
- Comparing Coverage Options Side by Side
- Packing Fragile Items for Moving to Reduce Damage Risk
- Filing Moving Damage Claims Step by Step
- Choosing Your Coverage Before Booking Primo Movers
- Frequently Asked Questions
Why Moving Insurance Coverage Matters Before Moving Day
Most people assume their belongings are covered during a move. In many cases, they are not, at least not fully. At Primo Movers, we see families and businesses in Tulsa discover coverage gaps only after something breaks on the truck.
The default protection a mover provides is often far less than people expect. Federal rules govern interstate household moves, and the Federal Motor Carrier Safety Administration’s household goods moving guidance explains the liability framework movers must follow.
Choosing coverage before booking gives you time to compare, ask questions, and avoid rushed decisions on moving day.
Basic Liability Coverage: What Movers Owe You by Default
Basic liability coverage is the minimum protection a moving company must provide. Basic coverage is generally based on weight rather than the actual value of what was damaged.
This means a 20-pound lamp and a 20-pound antique clock may be valued identically for claim purposes, even if one is worth a few hundred dollars and the other is worth several thousand. Basic coverage pays for weight, not worth.
Watch out: many customers assume the mover’s “included” protection will cover a full replacement. It usually does not. Ask for the exact per-pound figure in writing before the truck arrives.
Moving Insurance vs. Valuation Coverage: Know the Difference
These two terms are often used interchangeably, but they are not the same thing. Moving insurance usually refers to a separate policy, sometimes from a third-party insurer, that covers losses beyond the mover’s liability. Valuation coverage is the option a mover offers, and it sets the amount the mover must pay if something is damaged or lost.
Think of valuation as the mover’s obligation and insurance as your backup. A moving company may offer valuation options that change how much it owes per item or per pound. A separate insurance policy may cover gaps the mover’s valuation leaves open, depending on its terms.
Read the declared value section of your bill of lading carefully. This is where the coverage you selected is recorded, and it is the document that controls any claim.
Full Value Protection Moving: How It Works and Who Needs It
Full value protection is the highest level of valuation coverage most movers offer. Under this option, the mover’s obligation for damaged or lost items is set by the terms of the contract.
Pricing for coverage options depends on the move size, the total declared value, and the mover’s rate schedule. Request a quote from Primo Movers for current pricing.
Full value protection suits households with high-value furniture, electronics, artwork, or heirlooms. It also suits business moves where equipment and inventory carry significant replacement costs.
Pros and Cons of Full Value Protection
Pros:
- Covers the replacement or repair cost of damaged items, not just weight-based amounts
- Gives clearer protection for valuable or irreplaceable belongings
- Reduces the financial risk of a single damaged piece of furniture
Cons:
- Typically carries a higher premium than basic coverage
- Requires an accurate inventory and declared value, which takes time to prepare
- Claims may still involve depreciation, exclusions, or documentation requirements
Comparing Coverage Options Side by Side
The table below summarizes the coverage types most customers encounter. Use it to match each option to your move, then read the notes below the table, because the cost mechanics matter as much as the coverage label.
| Coverage Type | What It Pays | Typical Cost | Best For |
|---|---|---|---|
| Basic liability | Weight-based amount per pound | Usually included | Low-value, light household goods |
| Full value protection | Repair, replacement, or market value | Higher, priced by declared value | Valuable furniture and electronics |
| Third-party moving insurance | Losses beyond mover liability, per policy terms | Separate premium | Antiques, art, and high-value business assets |
| Self-insured or existing homeowner coverage | Depends on your current policy | Already paid | Customers checking existing protection first |
Before you choose, call your homeowner or renter’s insurer. Some policies cover belongings in transit, but many limit or exclude them. Confirm the terms in writing.
What actually drives the cost of each option
Ask the mover to break the quote into these components so you can see where the money goes:
Get every component of the quote in writing before you book.
How to book and coordinate packers on short notice
Short-notice packing succeeds or fails on the information you provide up front. To confirm availability and reduce surprises:
- Give an accurate scope: number of rooms, approximate box count, and a list of fragile or high-value items. Understating the scope is the most common cause of delays.
- State your deadline and access details: move date, elevator or stair access, parking, and whether the unit is ready to pack.
- Ask what is included: materials, labor, minimum hours, travel, and whether the crew will also label and inventory boxes.
- Confirm availability in writing: get the date, crew size, arrival window, and rate confirmed by email or text before you rely on it.
- Ask about the claim process before booking: who to contact, what documentation is required, and the deadline for reporting damage.
Get booking details in writing, including the date, crew size, and rate.
Match the option to the move, not the label
The right choice depends on what you own and how much time you have. If you are packing yourself under time pressure, basic liability plus a careful inventory may be enough for low-value goods, but full value protection is the safer match for fragile and high-value categories. If you are hiring packers, confirm in writing that their packing is covered under the valuation option you selected, that combination is what actually protects you when something breaks.
Packing Fragile Items for Moving to Reduce Damage Risk
Good packing lowers the chance that coverage will ever be needed, and it also protects your claim if something does break. Packing quality can affect coverage, so the way boxes are packed matters as much as safety. The practical goal is a repeatable system: decide what you pack, pack fragile items to a standard a professional would recognize, and label everything so the crew and your claim file can follow the trail.
Decide what to pack yourself versus delegate
Under time pressure, packing the wrong things badly can weaken a claim. Consider this split as a starting point:
-
Pack yourself: documents, passports, medication, jewelry, cash, laptops, and irreplaceable personal items. These should travel with you, not on the truck, and most movers exclude them from liability anyway.
-
Either, with care: clothing, books, linens, and non-fragile kitchen items. These are low-risk and good candidates for self-packing when time is short.
A common pattern is that households self-pack the easy rooms first and run out of time for the kitchen and fragile items, exactly the categories most likely to generate claims. Reverse that order.
Pack fragile items to a professional standard
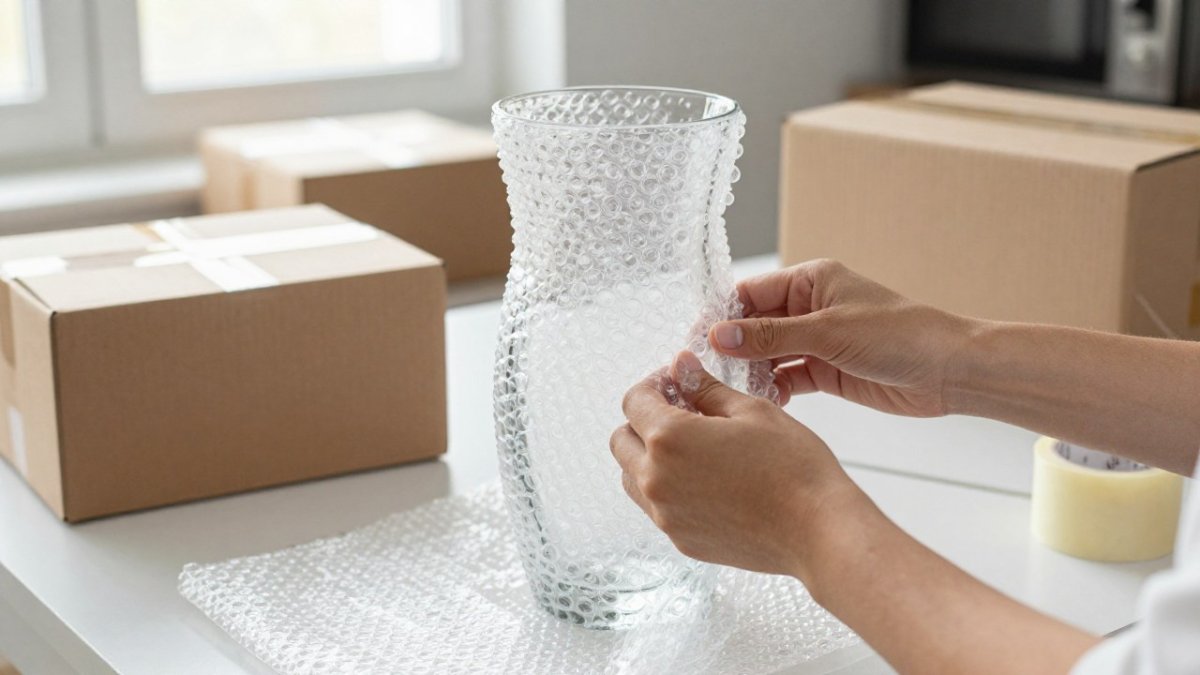
Wrap glassware and ceramics individually in packing paper, then bubble wrap. Place them in boxes with at least two inches of cushioning on all sides, and mark each box as fragile. Heavy items belong on the bottom, and wardrobe boxes work well for framed art and mirrors when stood upright. For kitchen items, pack plates on edge rather than flat, nest bowls with paper between them, and wrap stemware by the bowl with the stem supported.
A common mistake is overfilling boxes or using too little padding. Shake each box gently before sealing, and add more protection if anything shifts.
Use a room-by-room labeling and priority system
A simple labeling system does two jobs: it speeds up unloading and it creates the inventory record your claim depends on.
- Label every box with room, contents, and a priority number. Use a marker on at least two sides, and add a short contents list (for example, “Kitchen, stemware, fragile”).
- Assign priority 1 to essentials you need in the first 24 hours: medication, chargers, toiletries, bedding, basic cookware, and documents.
- Keep a master inventory list, paper or spreadsheet, with box number, room, contents, and estimated value for high-value items. Photograph the list and the labeled boxes before the truck leaves.
- Color-code or number by room so the crew can stage boxes in the right rooms at delivery and you can spot a missing box at a glance.
This system is also your claim file. If a box arrives crushed, the label, the photo, and the inventory entry together show what was inside and how it was packed.
Know how rushed or self-packing affects liability
Coverage and packing are linked. Basic liability is based on weight, so light, valuable items may recover little. Packing quality and prohibited items can affect how a claim is handled. Before you seal a box, confirm which items are excluded from the move and keep those with you. If you are packing under time pressure, prioritize professional packing for the fragile and high-value categories and self-pack the low-risk rooms.
Filing Moving Damage Claims Step by Step
If something breaks, act quickly and document everything. Most movers set strict deadlines for reporting damage, and delays can weaken a claim.
- Note the damage at delivery. Write it on the delivery receipt before signing, and describe it clearly.
- Photograph each damaged item. Capture the item, the packaging, and any visible labels from multiple angles.
- Gather proof of value. Receipts, appraisals, or photos showing the item before the move strengthen your claim.
- Submit a written claim. Follow the mover’s claim process and keep copies of everything you send.
- Track deadlines. Claims often must be filed within set time limits. Check your contract for the exact window.
Keep your inventory list updated during the move. It becomes evidence if a dispute reaches a formal review, and the Consumer Financial Protection Bureau’s moving guidance offers general advice on documenting consumer disputes.
Choosing Your Coverage Before Booking Primo Movers
Start by inventorying your belongings and estimating their replacement value. Then decide which items need full value protection and which can rely on basic coverage. Check your homeowner or renter’s policy, and ask whether a third-party policy would fill any remaining gaps.
Once you know your coverage needs, request written quotes that show each valuation option. Compare the costs against the value of what you are moving.
Get Quote today to review your coverage options with a Primo Movers representative before you book.
Frequently Asked Questions
What are the different moving insurance coverage options?
Moving coverage generally falls into a few categories, including liability-based coverage and full value protection, and some third-party options may supplement them. Costs and limits vary by company and by the coverage you select, so ask Primo Movers for current coverage details and a quote before your move date.
Is moving insurance the same as valuation coverage?
Not exactly. Valuation coverage is the term movers use for the liability they accept when your goods are damaged, and it is typically either released value or full value. Moving insurance is a separate policy that can cover losses beyond what the mover is required to pay. Many people use the terms interchangeably, but reading the actual valuation statement in your contract shows what the mover is responsible for. Ask Primo Movers how coverage applies to your belongings.
Should I buy extra coverage for fragile or valuable items?
Consider extra coverage if you are moving antiques, art, electronics, or heirloom furniture, since the replacement value of these items may exceed what basic coverage pays. Before buying, check whether your homeowners or renters policy already covers belongings in transit, and document valuable items with photos and receipts. Packing fragile items carefully also reduces the chance of a claim in the first place.
How do I file a claim for damaged items after a move?
Note any damage on the delivery inventory before you sign, and report it to Primo Movers in writing as soon as possible, ideally within the time limit stated in your contract. Include photos, the original receipt or proof of value, and your inventory list. Keep the damaged items and packing materials until the claim is resolved.
